
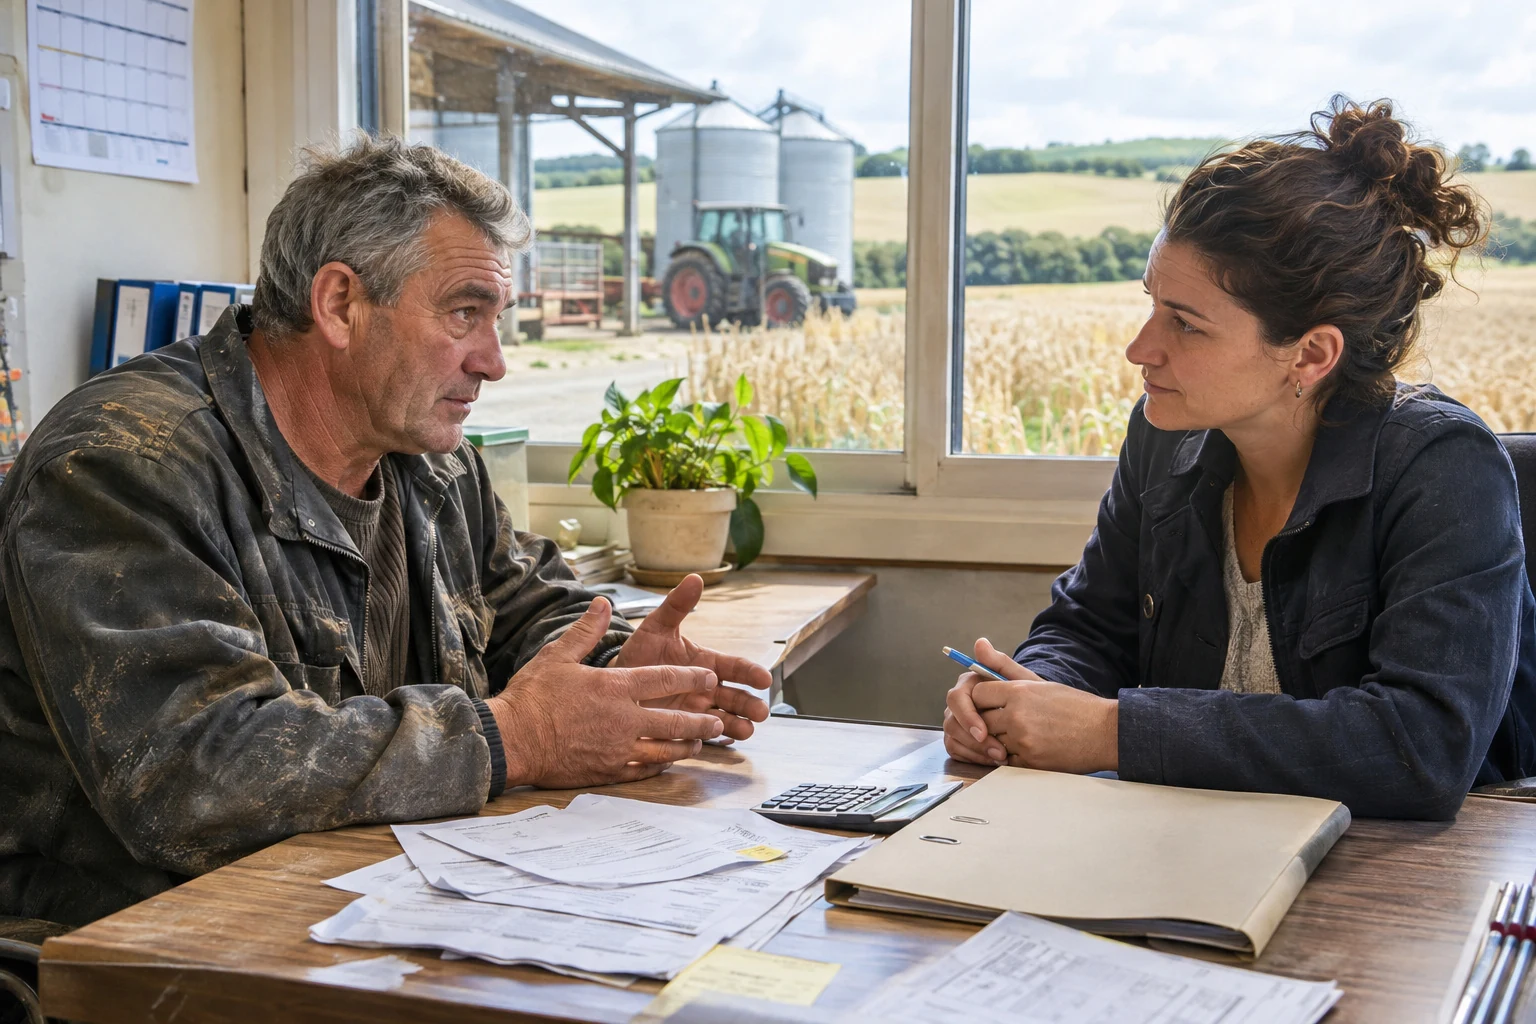
Show repayment capacity before relying on asset value
Farm-loan eligibility combines the borrower’s circumstances with the purpose and risk of the proposed financing. A lender may examine production experience, income, credit history, ownership documents and the ability of the farm to generate cash after necessary expenses. FSA’s Loan Assistance Tool explains eligibility questions for its programs, while a commercial lender applies its own underwriting standards. Owning valuable land can support an application, but collateral alone does not demonstrate that scheduled payments are affordable.
Clarify the security offered to each lender
Prepare a list of existing mortgages, equipment liens and guarantees before proposing assets as security. An asset’s purchase price, market value and amount accepted by the lender may be different. For a business entity, establish who can borrow, grant security and sign any personal guarantee. Ask how leased land, jointly owned property and livestock inventories will be treated. Understanding those questions early helps identify the evidence needed for a decision and reduces the risk of agreeing a purchase before the necessary financing has been assessed.
Eligibility guidance and agricultural underwriting
- FSA Loan Assistance ToolOfficial eligibility questions and product pathways for federal farm-loan applicants.Visit the organisation ↗
- Compeer agricultural credit informationExamples of the financial, management and collateral evidence considered by an agricultural lender.Visit the organisation ↗